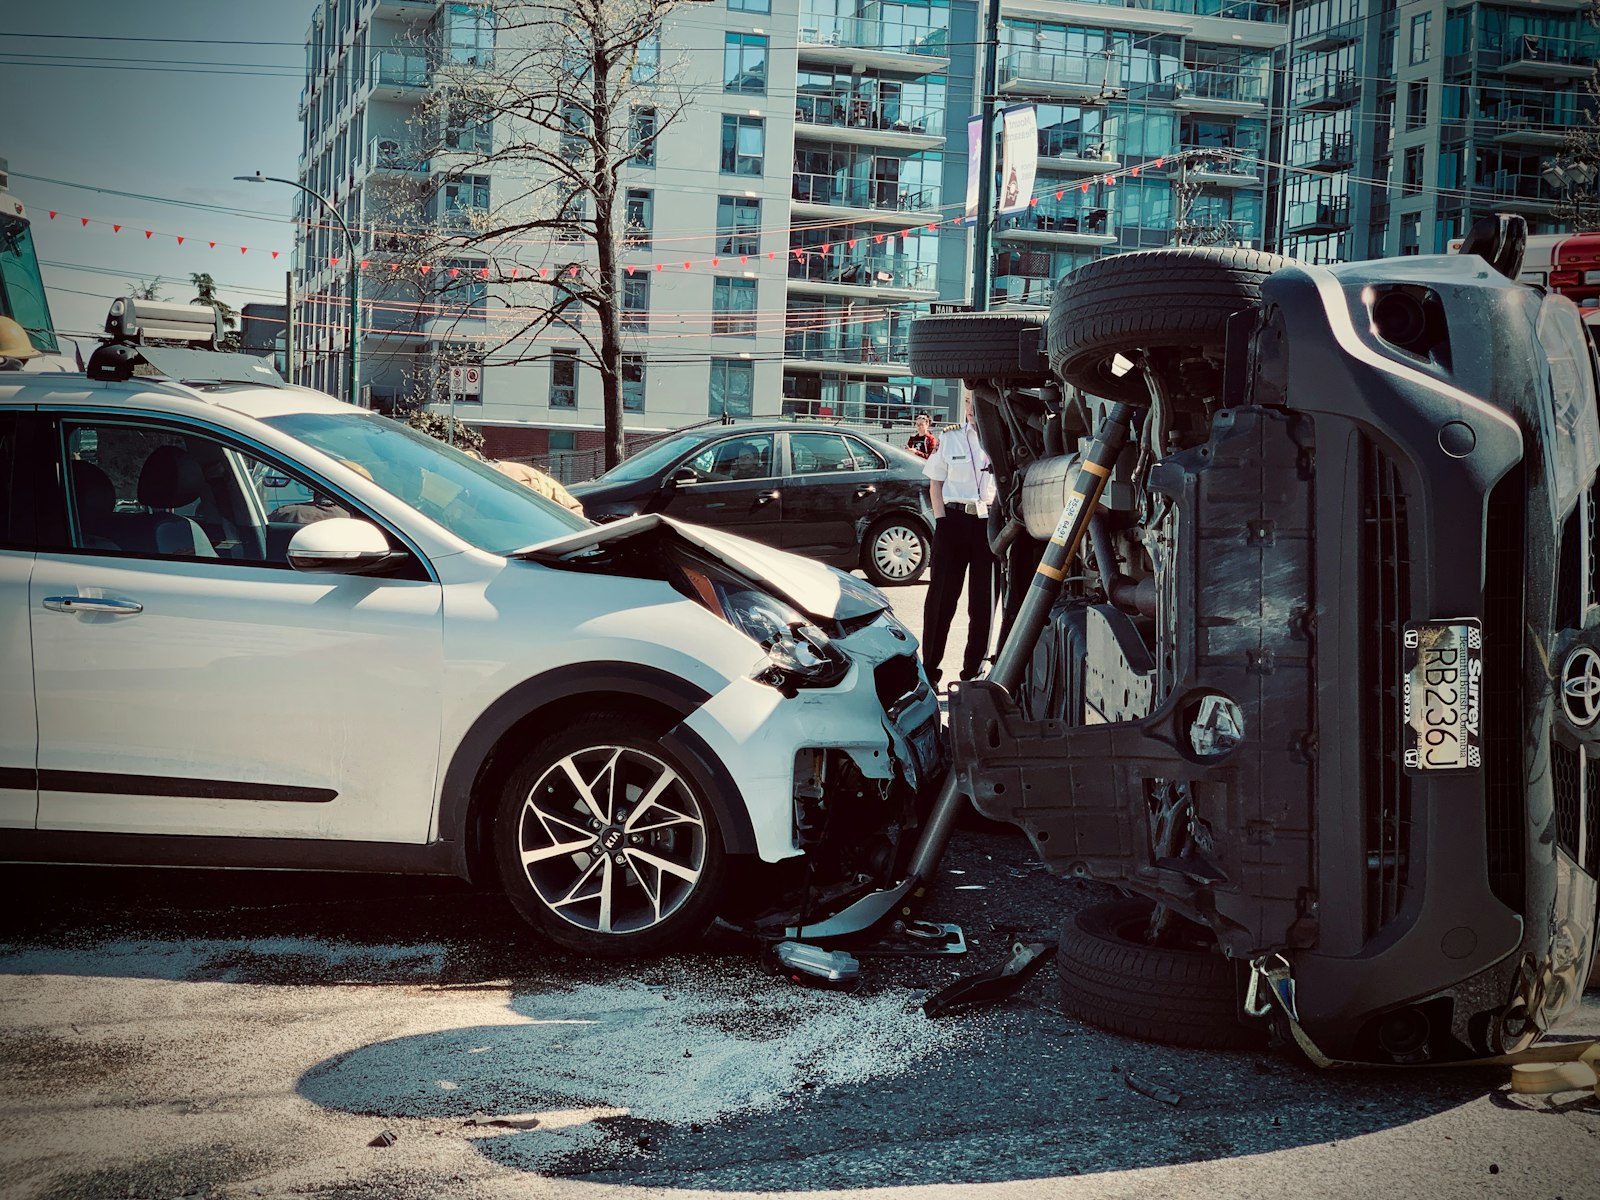
Yes, a $100,000 recovery is realistic for some California car accident cases and impossible for others, and the difference is not how the crash felt. It depends on four things: the injury and what the medical records show, the treatment you received and whether it was consistent, who was at fault and whether that is disputed, and the insurance available to pay. The last one is the hard ceiling. A driver carrying California’s minimum policy has $30,000 per person for injury, and no amount of pain changes that number unless there is another source of coverage.
The thing that decides these cases is the match between the injury and the insurance. A herniated disc with an epidural injection and a surgical recommendation, caused by a driver with a $100,000 policy, is a case where a six-figure demand is justified and the carrier knows it. The same injury caused by a driver with a $30,000 policy is a $30,000 case plus whatever your own underinsured motorist coverage adds. A sprained neck that resolved in six weeks of chiropractic care is not a $100,000 case against any policy, and a demand for that number will be treated as a reason not to negotiate. The first thing an attorney does on a file like this is find out how much insurance exists, because that answer decides what the case can be.
Can I get $100,000 for a car accident in California?
It is possible when the injury is serious and documented, the treatment supports it, fault is clear or mostly on the other driver, and there is at least $100,000 of insurance to reach. That insurance can be the other driver’s liability policy, your own underinsured motorist coverage, a commercial policy if the driver was working, or a combination. Against a single minimum $30,000 policy, a $100,000 recovery is not available no matter how bad the injury.
What a $100,000 injury case looks like
The number is driven by the injury and the medical record more than any formula. Cases that reach six figures in Los Angeles typically involve one of the following: a fracture that needed surgery or a long recovery, a disc herniation confirmed on MRI with injections or a surgical recommendation, a shoulder or knee tear that was repaired arthroscopically, a concussion with documented symptoms lasting months, or a soft tissue injury that was severe enough to need a year of care and left a permanent limitation.
Here is an example. A 38-year-old is stopped at a light on Nordhoff Street in Northridge and is rear-ended by a driver going 35. She goes to the ER at Northridge Hospital, has neck and low back pain, and after six weeks of physical therapy an MRI shows a herniation at L5-S1 pressing on the nerve. She gets two epidural injections and a pain management doctor says she is a surgical candidate if the pain returns. Medical bills paid come to $38,000. She missed five weeks of work at $1,100 a week. Fault is undisputed. The at-fault driver has a $100,000 policy. That is a case where a policy limits demand is justified and often paid.
Change one fact. The same crash, same injury, but the driver has a $30,000 policy and she has $100,000 in underinsured motorist coverage on her own policy. The case becomes $30,000 from the driver and a claim against her own carrier for the difference, up to $70,000 more. Same injury, same number, two negotiations.
Change a different fact. Same crash, but she waited three weeks to see a doctor, went to a chiropractor eight times, stopped, and never had an MRI. Bills are $4,200. That is not a $100,000 case against any policy, and the reason is the record, not the pain.
How the insurance picture sets the ceiling
Minimum coverage in California is $30,000 per person and $60,000 per accident under Vehicle Code 16056, and many drivers in Los Angeles carry exactly that. Above the minimum, common limits are $50,000, $100,000 and $250,000. Drivers with assets and umbrella policies are a small share of the road.
Your own underinsured motorist coverage, which carriers must offer under Insurance Code 11580.2, fills the gap up to your own limit, reduced by what the other driver paid. If you carry $100,000 in UM/UIM and the other driver paid $30,000, your own carrier owes up to $70,000 more if the injury supports it.
Commercial coverage changes everything. A driver on the clock for a delivery company, a rideshare driver with a passenger, a plumber in a company van, is covered by a commercial policy that often starts at $1 million. If the driver who hit you was working, finding that out is the most valuable step in the case.
Multiple defendants add coverage. A three-car chain collision on the 405 near Sherman Way may have two at-fault drivers and two policies.
What the insurance company will do with a six-figure demand
The carrier will look for a reason to cut it. Gaps in treatment, a delayed first visit, missed appointments, prior injuries, degenerative findings on the MRI, an argument that you were partly at fault, a claim that the chiropractic bills were inflated. On a $100,000 policy, the adjuster has authority to pay the limit only when the file leaves no good argument, and the demand has to answer each argument before it is made.
Carriers also use the Howell rule. Medical damages are limited to what was paid or owed, not billed. A $90,000 hospital bill that the health plan settled for $22,000 is $22,000 of medical damages. The pain and suffering component is argued from the injury, not the bill.
What you should do now
See a doctor within a day or two of the crash, and follow the plan. Get the MRI if the doctor orders it. Keep every appointment. Tell your attorney about your own policy’s UM/UIM coverage, and do not let anyone talk you out of using your health insurance. Ask whether the other driver was working. Stay off social media.
Mistakes that keep a case under $100,000
Settling early for the medical bills before the injury has declared itself. Treating only with a chiropractor when the symptoms call for an orthopedic evaluation. Signing a release with the driver’s carrier without first checking your own UIM coverage, because that release can waive the UIM claim. Exaggerating, which turns a strong file into a credibility fight.
Questions people ask next
What is the average settlement for a car accident in California? There is no reliable average, because settlements range from a few thousand dollars to policy limits depending on injury and coverage. The factors above drive the number, not a statewide figure.
Can I get $100,000 for whiplash? Rarely. Soft tissue injuries that resolve within a few months settle for far less. A whiplash injury that leads to a confirmed disc injury with injections is a different case.
Can I get more than the policy limits? Sometimes, through your own UIM coverage, a commercial policy, or a second defendant. Collecting against the driver personally beyond the policy is possible in theory and seldom worthwhile unless the driver has significant assets.
Manoukian Law Firm handles car accident cases throughout Los Angeles County, and the attorney personally identifies every policy that applies, builds the medical record the demand needs, and negotiates the claim with the driver’s carrier and your own. For a free consultation about what your case can be worth, call (818) 818-5031.