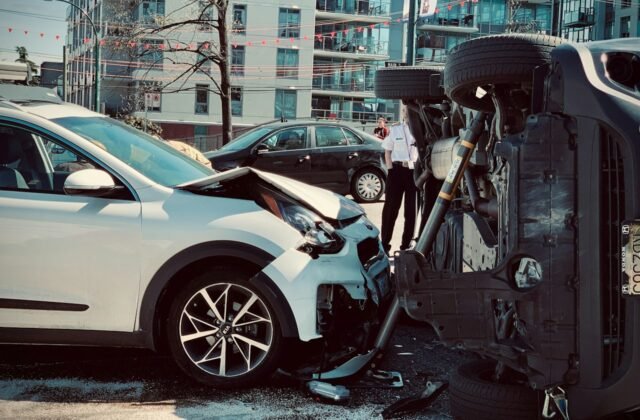
When a hit-and-run driver kills someone in Los Angeles and is not caught, the family is told, often by the first adjuster they speak to, that there is no one to claim against. That is usually wrong. California treats a hit-and-run driver as an uninsured motorist, which means the uninsured motorist coverage on the decedent’s own auto policy, and sometimes on a household member’s policy, pays the wrongful death claim. There are specific reporting rules that have to be met quickly, and a deadline for the uninsured motorist claim that is different from the ordinary two years. Los Angeles has one of the highest hit-and-run rates of any city in the country, and most of these cases that are lost are lost on the procedure, not the facts. Here is how the coverage works and what has to happen in the first days.
Hit-and-run drivers are uninsured motorists
Insurance Code section 11580.2 requires every California auto policy to include uninsured motorist coverage unless the insured rejected it in writing. The statute defines an uninsured motor vehicle to include a vehicle whose owner and operator cannot be identified, which is the legal description of a hit-and-run. If the decedent carried uninsured motorist bodily injury coverage, that coverage pays the wrongful death damages the unidentified driver would have owed, up to the policy limit.
The heirs’ claim is the same wrongful death claim they would bring against an identified driver: lost financial support, household services, funeral expenses, and the loss of love, companionship and guidance, as explained in our article on who can file. The difference is that the insurer stands in the driver’s shoes, and the dispute, if there is one, is resolved by arbitration rather than a jury.
Which policies apply
The decedent’s own auto policy, first. A pedestrian or cyclist killed by a hit-and-run driver is covered by his or her own auto policy’s uninsured motorist coverage even though no car of theirs was involved; the coverage follows the person.
A resident relative’s policy. Uninsured motorist coverage typically extends to family members who live in the insured’s household. A young adult living at home, a spouse, a parent: if the decedent lived with someone who had a policy, that policy may apply, and it may have higher limits.
The policy on the vehicle the decedent was in, if the decedent was a passenger in someone else’s car.
Where more than one policy applies, California generally does not allow the limits to be added together, but the policy with the highest limit controls, and the order in which they respond is set by the policies’ terms.
The three requirements for a hit-and-run uninsured motorist claim
Section 11580.2(b) imposes conditions on hit-and-run claims that do not apply to ordinary uninsured motorist claims, and insurers enforce them strictly.
Physical contact. The hit-and-run vehicle must have made physical contact with the decedent or the vehicle the decedent was in. A driver who ran a cyclist off the road without touching him is not a hit-and-run under the statute, though independent witnesses can sometimes satisfy a related “phantom vehicle” provision.
Police report within 24 hours. The accident must be reported to the police or the California Highway Patrol within 24 hours. In a fatal crash in Los Angeles this is almost always satisfied by the response of LAPD or CHP to the scene, but confirm that a report exists and get the report number.
Notice to the insurer within 30 days. A statement under oath that the insured has a cause of action against an unidentified driver must be filed with the insurer within 30 days of the accident. This is the one families miss. It is not the same as reporting the death to the insurer; it is a specific sworn statement, and the deadline is 30 days from the crash, not from when the family learns about the coverage.
The deadline for the uninsured motorist claim
Section 11580.2(i) sets a two-year limit, but the clock is satisfied differently than in an ordinary lawsuit. Within two years of the accident, one of three things must happen: suit is filed against the uninsured driver, the insurer agrees in writing to the amount of the claim, or a formal demand for arbitration is made to the insurer. In a hit-and-run with no identified driver, there is no one to sue, so the demand for arbitration is what stops the clock. A letter asking the insurer to evaluate the claim does not count. A claim file that has been open for two years with an adjuster “still reviewing” does not count. The written arbitration demand has to be sent, and it has to be sent in time.
If the driver is caught
LAPD’s Valley Traffic Division and the CHP investigate fatal hit-and-runs, and Los Angeles has a standing reward program for information leading to the identification of hit-and-run drivers. When a driver is identified, the case changes: the claim proceeds against the driver’s own liability insurance, the criminal case produces evidence and restitution orders, and if the driver was intoxicated, punitive damages become available through the survival action. The uninsured motorist claim remains as a backstop if the driver’s coverage is inadequate or nonexistent, which is common, because drivers who flee often do so because they are uninsured, unlicensed or impaired.
Other sources of compensation
The California Victim Compensation Board reimburses funeral and burial expenses for victims of violent crime, which includes vehicular manslaughter and felony hit-and-run, up to a statutory cap, and the application is separate from the insurance claim. Life insurance, accidental death benefits on credit cards and employer plans, and Social Security survivor benefits are all checked. None of these reduce the uninsured motorist recovery.
What to do now
Get the police report number and the name of the investigating detective. Locate the decedent’s auto policy and the policies of everyone in the household; the declarations pages show the uninsured motorist limits. Send the sworn 30-day notice to each potentially applicable insurer. Preserve the decedent’s phone, which may have location data, and canvass for video: traffic cameras, businesses, doorbell cameras along the route. Request the coroner’s file when it is available. Identify all heirs under section 377.60 and establish a personal representative for the survival action. Calendar the two-year arbitration deadline from the date of the crash.
Key points
A hit-and-run driver who is never identified is an uninsured motorist under Insurance Code 11580.2. The decedent’s own policy, and often a household member’s, pays the wrongful death claim up to the limit.
Three conditions: physical contact, a police report within 24 hours, and a sworn notice to the insurer within 30 days.
The two-year deadline is satisfied only by suit, a written agreement, or a formal arbitration demand. An open claim file is not enough.
If the driver is later identified, the claim proceeds against the driver too, with punitive damages available for drunk driving.
Funeral costs may be reimbursed by the Victim Compensation Board separately.
Frequently asked questions
My mother was walking and did not own a car. Is there any coverage? If she lived with a relative who had an auto policy, that policy’s uninsured motorist coverage likely extends to her. If not, the claim depends on identifying the driver, and the investigation and reward program matter more.
The insurer says the 30-day notice was late because we called them on day 35. Is the claim lost? Not necessarily. Courts have excused late notice where the insurer was not prejudiced and where the insured did not know the coverage applied, but it is a fight. Send the notice now, in the required form, and have the issue evaluated.
Does the uninsured motorist insurer fight the claim? Often, yes. It is the family’s own insurer, but on an uninsured motorist claim it is in the position of the other driver and defends accordingly. The claim is prepared and presented like any wrongful death case.
How long do we have? Thirty days for the sworn notice; two years from the crash for the arbitration demand; two years for suit against an identified driver; six months for a government claim if a dangerous road condition contributed.
Manoukian Law Firm, P.C., Chatsworth, California. Free consultation. No fee unless we win. Past results do not guarantee a similar outcome.